Most entrepreneurs who have registered foreign companies, including companies in the United Kingdom, are able to obtain a certificate of tax residence for their company.
What is a Tax Residence Certificate in the United Kingdom?
A certificate of tax residence is required to obtain tax benefits in another country if the company pays tax on its foreign income in the United Kingdom.
This certificate helps confirm tax residence in the United Kingdom for another country.
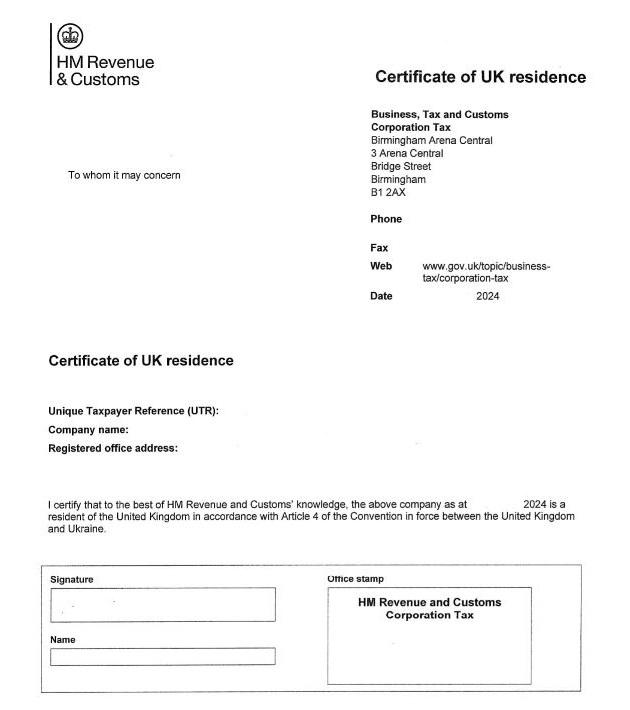
Certificate of Residence and Letter of Confirmation
Depending on the purpose of confirming tax residence, HMRC may issue a Certificate of Residence or a Letter of Confirmation. A Certificate of Residence is used to confirm entitlement to tax relief under the relevant double taxation agreement (DTA). If confirmation of UK tax residence is needed for another purpose, HMRC may provide a Letter of Confirmation.
Who needs such a certificate?
A certificate of residence may be needed if the company is a UK resident and the United Kingdom has a double taxation agreement with the country in which the company conducts business. For example, the Convention between the Government of Ukraine and the Government of the United Kingdom of Great Britain and Northern Ireland for the avoidance of double taxation and the prevention of fiscal evasion with respect to taxes on income and capital gains was signed on 10.02.1993 and entered into force on 11.08.1993.
On 09.10.2017, a Protocol introduced amendments to the Convention. The Protocol was aimed at avoiding double taxation of income of individuals and legal entities arising in both states.
How to obtain a Tax Residence Certificate in the United Kingdom?
To obtain a Tax Residence Certificate, a request must be submitted to HMRC through the relevant online service, providing information about the company, its activities, and the grounds for confirming its UK tax residence. For newly established companies that have not yet filed a Corporation Tax Self Assessment return, HMRC may request additional information about the directors, shareholders, and the reasons the company considers itself a UK tax resident.
Company registration in the United Kingdom by itself does not mean automatic receipt of a tax residence certificate. HMRC checks the grounds on which the company is considered a UK resident for the purposes of the relevant tax agreement.
According to HMRC's internal instructions in the internal manual, when an officer receives a request for a certificate of residence, they must first check:
The grounds for considering the company a resident of the United Kingdom, including under which double taxation agreement and article of that agreement.
The date or period for which the client is requesting the certificate of residence.
HMRC usually certifies that a person is a UK resident as of the date the certificate is issued. However, HMRC may also certify that a person was a resident for a certain period, provided that period does not end later than the date the certificate is issued (HMRC cannot certify that a person will be a UK resident for any period in the future, since it cannot verify whether this will be the case).
The format of the certificate may vary slightly, but it usually confirms:
The company name
The registered address
That the company is a UK resident for tax purposes or under a specific tax agreement or convention.
To obtain a Tax Residence Certificate in the United Kingdom, contact Maira Consult.
